Building a finance function that does not depend on key individuals
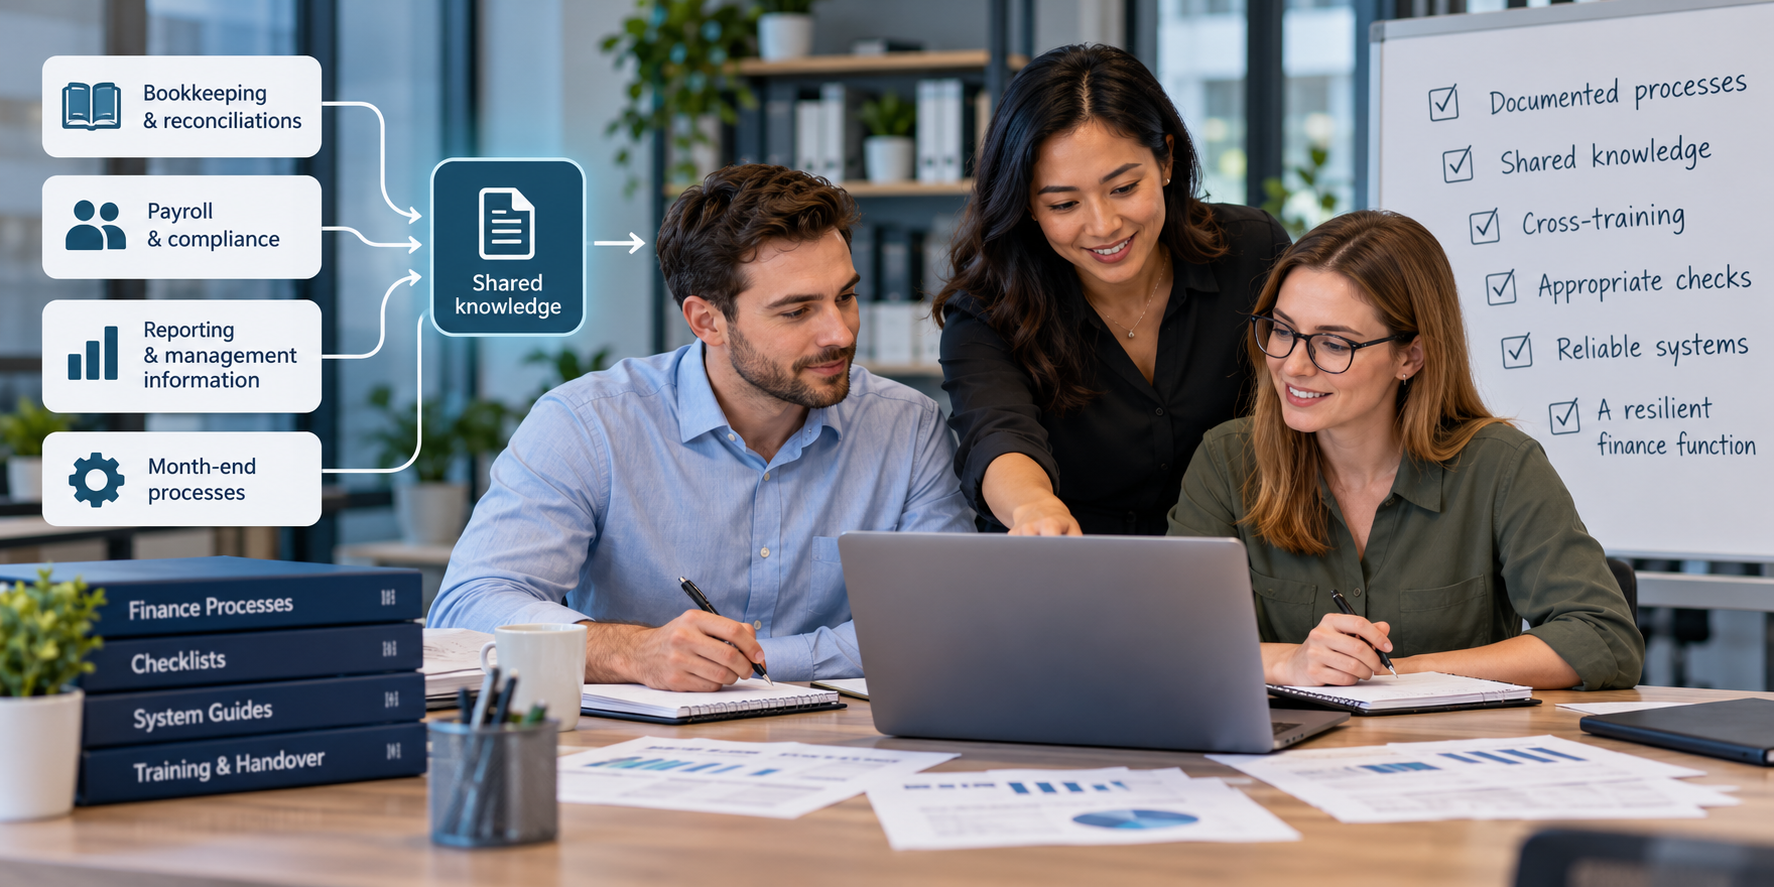
A finance function should keep the business running, even when a key finance employee is unavailable.
Yet in many growing businesses, one or two people hold most of the financial knowledge. One person may manage bookkeeping and reconciliations. Another may handle payroll and compliance. Someone else may take responsibility for month-end reporting, financial statements or management reports.
This can work when a business is small. As the business grows, however, relying heavily on a few people can create a real operational risk.
If one of these employees resigns, takes extended leave or suddenly becomes unavailable, the business may struggle to keep important finance tasks on track. The remaining team may not know how to complete certain processes, where to find supporting information or what needs to happen before they can finalise reports.
The problem is not the people themselves. They may be experienced, capable and trusted members of the team. The problem is that too much of the finance function depends on their individual knowledge and availability.
When businesses do not document processes, share responsibilities or maintain backup capacity, one person’s absence can put pressure on the entire finance function.
A stronger finance function spreads knowledge, shares responsibilities and builds enough capacity to keep essential finance activities moving when people change.
The hidden cost of key-person dependency
Key-person dependency can go unnoticed when bookkeeping, payroll and reporting are completed on time by the usual finance team members.
Bookkeeping stays up to date. Reconciliations get completed. Payroll gets processed. Reports get prepared. Everything appears to be under control.
The problem often becomes clear only when the person responsible becomes unavailable.
The business may suddenly realise that no one else knows how to prepare the monthly accounts, complete certain reconciliations, find supporting information or finalise financial reports.
This can delay reporting and put additional pressure on the rest of the finance team. Important tasks may have to wait until the usual person returns. Alternatively, another employee may need to spend valuable time trying to understand a process they do not normally handle.
The risk becomes greater as the business grows.
More transactions, reporting requirements and financial complexity increase the workload of the finance function. If that work still depends on the knowledge of one person, the business becomes increasingly exposed when that person is unavailable.
The answer is not to eliminate individual expertise. It is to make sure important finance processes do not depend on individual expertise alone.
A resilient finance function needs documented processes, shared knowledge and enough capacity for another trained person to step in when required.
Turn individual knowledge into shared knowledge
The first step is to make sure important finance knowledge does not sit with just one person.
Businesses should document key bookkeeping processes, reconciliations, payroll procedures, reporting requirements and month-end tasks. Another member of the finance team should be able to understand what needs to happen, find the relevant information and follow the required steps.
For example, if only one person knows how to prepare the monthly accounts, complete specific reconciliations or put together management reports, their absence can quickly create a gap.
Documenting these processes gives the business a clear reference point. It also helps another trained finance professional take over when responsibilities change or the business needs additional support.
This does not mean creating lengthy manuals for every finance task. Businesses should focus on documenting key processes such as bookkeeping, reconciliations, payroll and month-end reporting, so another trained team member can access the information and complete the task when needed.
When businesses share knowledge and document processes, they reduce their reliance on individual memory. They also make it easier to onboard new team members, transfer responsibilities and maintain consistent finance processes as the business grows.
Build processes that others can follow
Documenting a process is only the first step. The business also needs to make each process clear enough for another trained finance professional to follow.
In some businesses, employees complete finance tasks based on personal knowledge rather than a consistent process. One person may know exactly how to complete a reconciliation, prepare a monthly report or check the accounts before month-end. However, another team member may struggle to complete the same task without their help.
This can create unnecessary dependence on one person.
A better approach is to review the finance tasks that happen regularly and make sure each one has a clear process. The steps should be easy to follow, responsibilities should be clear, and the information needed to complete the task should be accessible.
A simple question can help identify the gaps:
Could another trained person take over this task and complete it correctly if the usual person was unavailable? If the answer is no, the business may need to document the process more clearly, share the responsibility or train another team member.
The goal is not to remove individual expertise. It is to make sure the finance function can continue to operate without relying on one person’s memory or way of working.
Make sure important finance tasks have the right checks
A strong finance function also needs appropriate checks.
When one person prepares, approves and checks the same financial information, the business has limited independent review. This can increase the risk of errors going unnoticed.
For example, the person who prepares a reconciliation should not always be the only person who reviews it. Similarly, the business should have an appropriate review process for important financial reports before management uses them to make decisions.
As a business grows, these checks become increasingly important. More financial activity means more information to review and more opportunities for errors to occur.
Smaller businesses may not have enough people to separate every finance task between different employees. In these cases, management can provide an additional review where full separation is not practical.
The goal is not to add unnecessary steps to every finance process. It is to make sure the business reviews important financial work appropriately and does not rely entirely on one person’s decisions.
This gives people clear responsibilities while maintaining appropriate checks across the finance function.
Cross-training creates continuity
Documentation only helps when other people know how to use it.
Cross-training ensures that more than one person understands the finance tasks that matter to the business. If someone becomes unavailable, another trained team member can step in without having to start from scratch.
This does not mean everyone needs to know every part of the finance function. Instead, businesses should identify the tasks that cannot wait and make sure more than one person can handle them.
For example, if one person manages monthly reporting, another team member should understand the process well enough to prepare or support the report when needed. The same applies to bookkeeping, reconciliations, payroll and other regular finance activities.
Cross-training also makes it easier to transfer responsibilities when someone leaves the business or moves into a different role.
The result is a finance function that relies on shared knowledge rather than one person’s memory. People can step in when needed, and important finance work can continue without unnecessary disruption.
Technology helps, but it is not the whole answer
The right technology can make finance processes more efficient, but it cannot replace a well-structured finance function.
Accounting systems can reduce manual work, improve access to financial information and make recurring tasks easier to manage. However, if only one person knows how the system works or how to use the information, the business can still remain dependent on that person.
Before introducing new technology, businesses should understand the process they want to improve. They should know who owns each task, what information they need and where they need checks.
Technology can then support the process through automation, consistent workflows and easier access to financial information.
The goal is to build a finance function where technology supports the team, rather than a system that only one person knows how to operate.
Test how well your finance function can operate without one person
One simple way to identify key-person dependency is to ask what would happen if a key finance employee became unavailable tomorrow.
- Could someone else complete the bookkeeping?
- Could another team member handle the reconciliations?
- Could payroll still run on time?
- Could the monthly reports still be prepared?
- Does more than one person know where to find the necessary information?
- Are important finance processes documented and easy to follow?
These questions can help identify areas where the business may rely too heavily on one individual.
A resilient finance function does not require everyone to know everything. It requires the right processes, shared knowledge, appropriate checks and enough trained people to keep important finance activities moving.
Build a finance function that can keep moving
Building a finance function that does not depend on one person takes more than hiring additional staff. It requires clear processes, shared knowledge, reliable systems and access to the right finance expertise.
For many growing businesses, building this capability in-house can become difficult. This is where we at Accario can help.
At Accario, we build continuity into the way we work, with trained backup staff ready to step in when needed. Combined with our ISO-certified processes and four-tier review framework, this helps keep your finance operations consistent, accurate and moving forward, even when the unexpected happens.
Talk to our team about building greater continuity into your finance function.
Follow Us


Most Popular


Are you ready
to get your time
back?
Yes! Accario will help you
focus on your business
More smarts, more efficiencies,
with more benefits.