Payday Super and the end of Quarterly Super
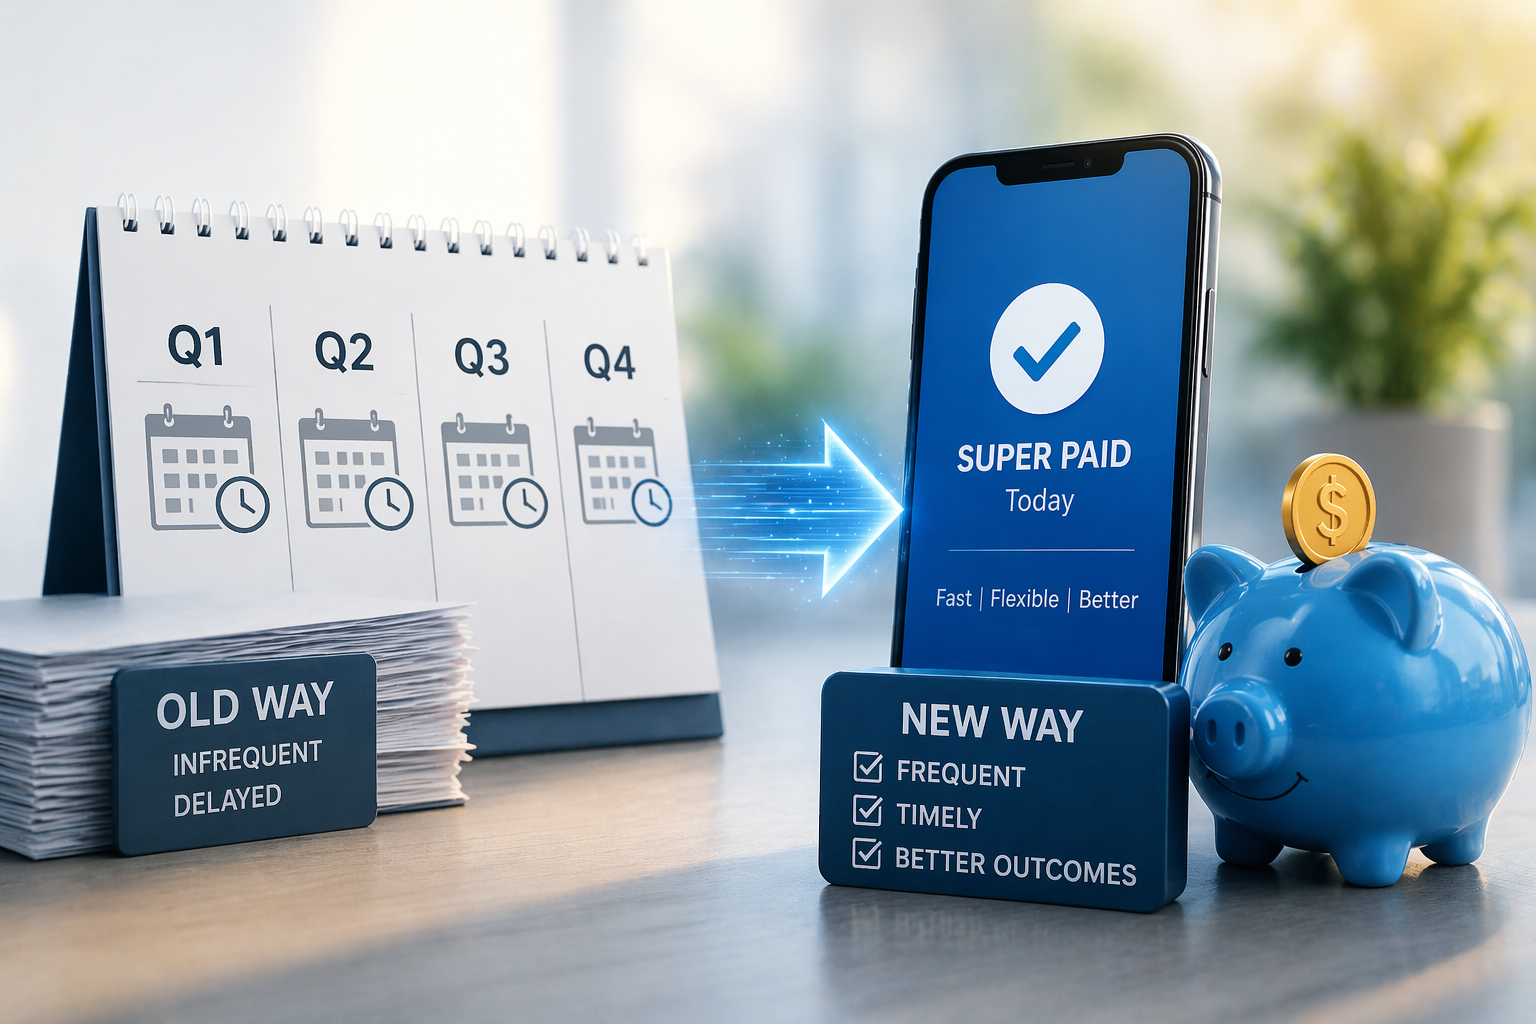
Payday Super is not just a small compliance update. It changes the basic rhythm of employer super payments in Australia. Employers usually pay super quarterly under the current system. From 1st July 2026, employers must make super contributions in line with each pay cycle, so they reach the employee’s fund within the required timeframe, generally within 7 business days of payday. There is a limited exception for a new employee’s first contribution, where the first contribution can be made within 20 business days.
The intent behind the reform is straightforward. It aims to reduce unpaid super, improve transparency for employees, and enable earlier detection of non-compliance through closer alignment between payroll reporting and super fund data. In practice, Payday Super is not just a rule change. It changes how payroll works day to day. Payments need to move faster, employee and fund details must be accurate, and there is less time to fix errors before super falls due.
What changes in July
Until 30th June 2026, employers generally pay super at least four times a year, with quarterly due dates of 28th October, 28th January, 28th April, and 28th July. A contribution counts as paid only when the super fund receives the contribution, not when the employer starts the payment.
From 1st July 2026, that quarterly structure ends for ongoing super guarantee obligations. The Payday Super reforms will apply from 1st July 2026, and official guidance says employers must pay super in line with each pay cycle, so contributions reach the employee’s fund within the required timeframe, generally within 7 business days. Put simply, when employers pay wages weekly, they pay super weekly. When employers pay wages fortnightly, they pay super fortnightly. The commonly cited exception is the first contribution for a new employee. Employers can make the first contribution within 20 business days of paying wages. Longer timeframes may apply in certain defined circumstances, which means employers should not assume every payment always has the same deadline.
The most important practical point is that Payday Super is a receipt rule, not just a sending rule. The compliance test is whether the contribution reaches the employee’s fund in time. That detail matters because it turns payment method, settlement speed, rejected contributions, and data quality into core compliance issues rather than back-office administration.
Why the policy is changing
Treasury’s public explanation is blunt: unpaid super remains a large problem. Estimates show that $5.2 billion of super went unpaid in 2021-22, and the policy aims to reduce that gap by linking super to each pay cycle instead of leaving it to quarterly deadlines. The change helps employees see their super sooner, allows issues to be picked up earlier, lets super funds invest contributions faster, and reduces the chance of employers building up large unpaid amounts.
Under the old system, employers could legally hold super until the quarter’s due date. Under the new system, that delay largely disappears. So, the reform is doing two things at once: improving employee outcomes and reducing the amount of unpaid super that can build up before anyone notices. It will also detect non-payment sooner by matching data reported by employers with data reported by super funds.
What the operational shift means
Super becomes part of every pay cycle
For payroll teams, Payday Super turns super from a periodic task into part of every pay cycle. The Australian Taxation Office (ATO) already uses Single Touch Payroll (STP) to receive payroll information when employers pay employees. Under Payday Super, ATO guidance indicates that employers will report qualifying earnings (QE) and super liability through STP, and digital service providers will need to update products to support new reporting requirements through STP. In other words, this is not only a payment-frequency change. It is also a data and reporting change.
Systems and reporting will need to adapt
The technical side of the reform is easy to underestimate. Systems will need to handle higher volumes, process payments faster, improve how errors are managed and fixed, and align with updated SuperStream standards. These updates support near real-time payments, clearer error messages, and better member verification. They are also expected to shorten allocation and error response timeframes, with super funds expected to allocate or return contributions within 3 business days. This means problems will show up faster, but they will also need to be fixed faster.
Changes for small business payment methods
There is also a practical impact for smaller employers. The ATO will retire the Small Business Superannuation Clearing House from 1st July 2026. New registrations closed on 1st October 2025, and existing users now need to move to another payment method before the deadline.
Cash flow timing becomes more frequent
For many businesses, this will mean more frequent and earlier cash outflows. That inference follows directly from the move away from quarterly due dates and is consistent with ATO guidance telling employers to make a cash-flow plan ahead of 1st July 2026. Some firms may find the overall annual cost unchanged but the timing less forgiving, because the old quarter-end “float” largely disappears.
Compliance risk becomes more immediate
Employers are liable for the Super Guarantee Charge if contributions do not reach the fund on time. Under the Payday Super changes, the Super Guarantee Charge (SGC) framework aligns with the payday model and once SGC applies, interest, administrative charges, and penalties may also apply. The late payment offset will no longer be available once Payday Super starts. Late super can also create workplace relations risk in some cases.
How employers can prepare now
The official message from Fair Work and the ATO is consistent: start with payroll processes, not slogans. Employers are being told to review payroll systems and business processes, check employee super details, review payroll governance, and make a plan for cash flow. Employers should review their STP software and correctly map pay codes so they can meet the new reporting requirements.
In practical terms, the preparation work is fairly clear. First, confirm that employee fund details are current and accurate. Second, confirm that your payroll system and any clearing or payment processes can support the new timing. Third, test how your team will identify and fix rejected, returned, or mismatched contributions. Fourth, if you use the SBSCH, complete your transition before it closes. Fifth, update internal controls so payroll, finance, and reporting teams all follow the same deadline logic: a contribution is compliant when the fund receives it, not when you create a batch file.
The transition path below brings together key preparation steps, the SBSCH closure timeline, and the legislated start date into a clear, practical approach.
Side-by-side comparison
| Topic | Current system until 30th June 2026 | Payday Super from 1st July 2026 |
| Timing | Super is generally paid quarterly, with due dates on 28th October, 28th January, 28th April, and 28th July. | Super is paid with each pay cycle, and contributions generally must reach the employee’s nominated fund within 7 business days of payday. |
| When payment counts | When the super fund receives the contribution | Same rule applies – receipt by the fund determines compliance |
| Reporting and visibility | STP already gives the ATO payroll and super information, and the ATO uses STP data to assess obligations. | Employers will report qualifying earnings and super liability through STP and will match employer and fund data sooner to detect unpaid super earlier. |
| Exceptions | Quarterly rules are the normal rule set. | There are limited longer-timeframe cases; the first contribution for a new employee can be made within 20 business days. |
| Enforcement | If super is not paid on time, in full, and to the right fund, the employer can face the Super Guarantee Charge. | If the fund does not receive the contribution within the required timeframe, the employer can face the Super Guarantee Charge; the late payment offset will no longer be available once Payday Super begins. |
Payday Super leaves less room for delays and errors in payroll and super processing. At Accario, we help you stay ahead with structured, tech-enabled payroll and finance support, keeping your operations accurate and compliant.
Contact us to get started and keep your payroll running smoothly under the new requirements.
References
- Payday Super: New rules starting 1 July 2026 – Fair Work Ombudsman. Available at: https://www.fairwork.gov.au/newsroom/news/payday-super-new-rules-starting-1-july-2026
- Department of the Treasury; Payday Super, Payday Super | Treasury.gov.au. Available at: https://treasury.gov.au/publication/p2024-581438.
- Payday super | Treasury beta website, Treasury.gov.au, 2025. Available at: https://beta.treasury.gov.au/policy-topics/superannuation/payday-super
- Payday Super | ATO Software Developers, Ato.gov.au, Mar. 18, 2026. Available at: https://softwaredevelopers.ato.gov.au/PaydaySuper
- Single Touch Payroll | ATO Software Developers, Ato.gov.au, Sep. 18, 2024. Available at: https://softwaredevelopers.ato.gov.au/STP
- Australian Taxation Office, “Super payment due dates,” www.ato.gov.au. Available at: https://www.ato.gov.au/businesses-and-organisations/super-for-employers/paying-super-contributions/super-payment-due-dates
Follow Us


Most Popular


Are you ready
to get your time
back?
Yes! Accario will help you
focus on your business
More smarts, more efficiencies,
with more benefits.